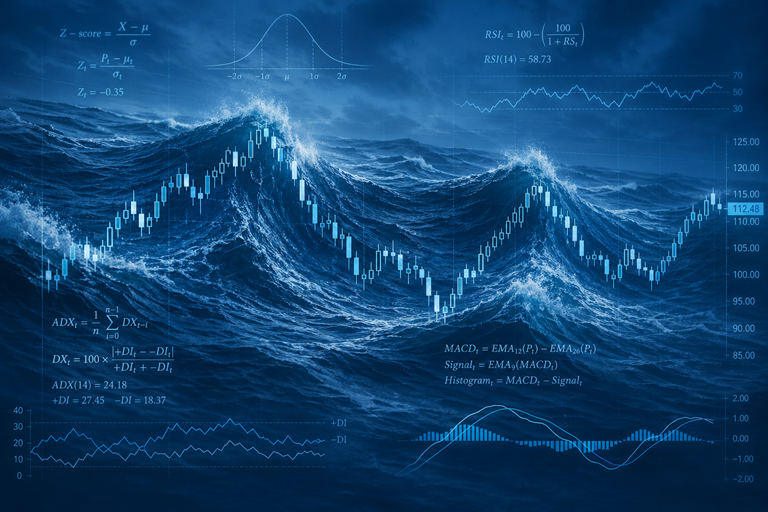
Markets move in waves, exhibiting recurring dynamics across trend, volatility, momentum, and liquidity.
Market outcomes are asymmetrically distributed, with strong dispersion across stocks driven by shifting liquidity and risk-appetite.
Statistical models identify market patterns and translate them into signals for systematic decision-making.
Identifies extreme price dislocations, targeting mean-reversion with limited downside risk.
Captures sustained trends with persistent price strength and momentum confirmation.
Captures pullbacks within strong uptrends to improve entry quality and risk-reward.
Decisions derived from price trends and market regimes, reducing subjective judgment.
Long-only strategies designed for compounding across market cycles.
Systematic position sizing and exit management to limit drawdowns.
Models are refined using evolving market dynamics for stability across regimes.
Proprietary models generate signals from historical and real-time market data inputs.
Rule-based execution through automated systems with minimal human discretion.
Each position is managed within predefined exposure limits and stop-loss thresholds.
Akash focuses on developing algorithmic trading strategies for Indian equities, combining research, modeling, and automated execution. His work emphasizes continuous refinement of quantitative models and disciplined capital allocation.
Prior to founding SigQuant, he worked at leading global investment firms, including Blackstone and General Atlantic, gaining exposure to structured investing and risk frameworks. He also served as Head of Strategy and M&A at Disney Star. He started his career as a management consultant at Kearney and holds a B.Tech in Computer Science from IIT Bombay.